03 · Daily Special · Signal 3
A positive week with a narrow doorway
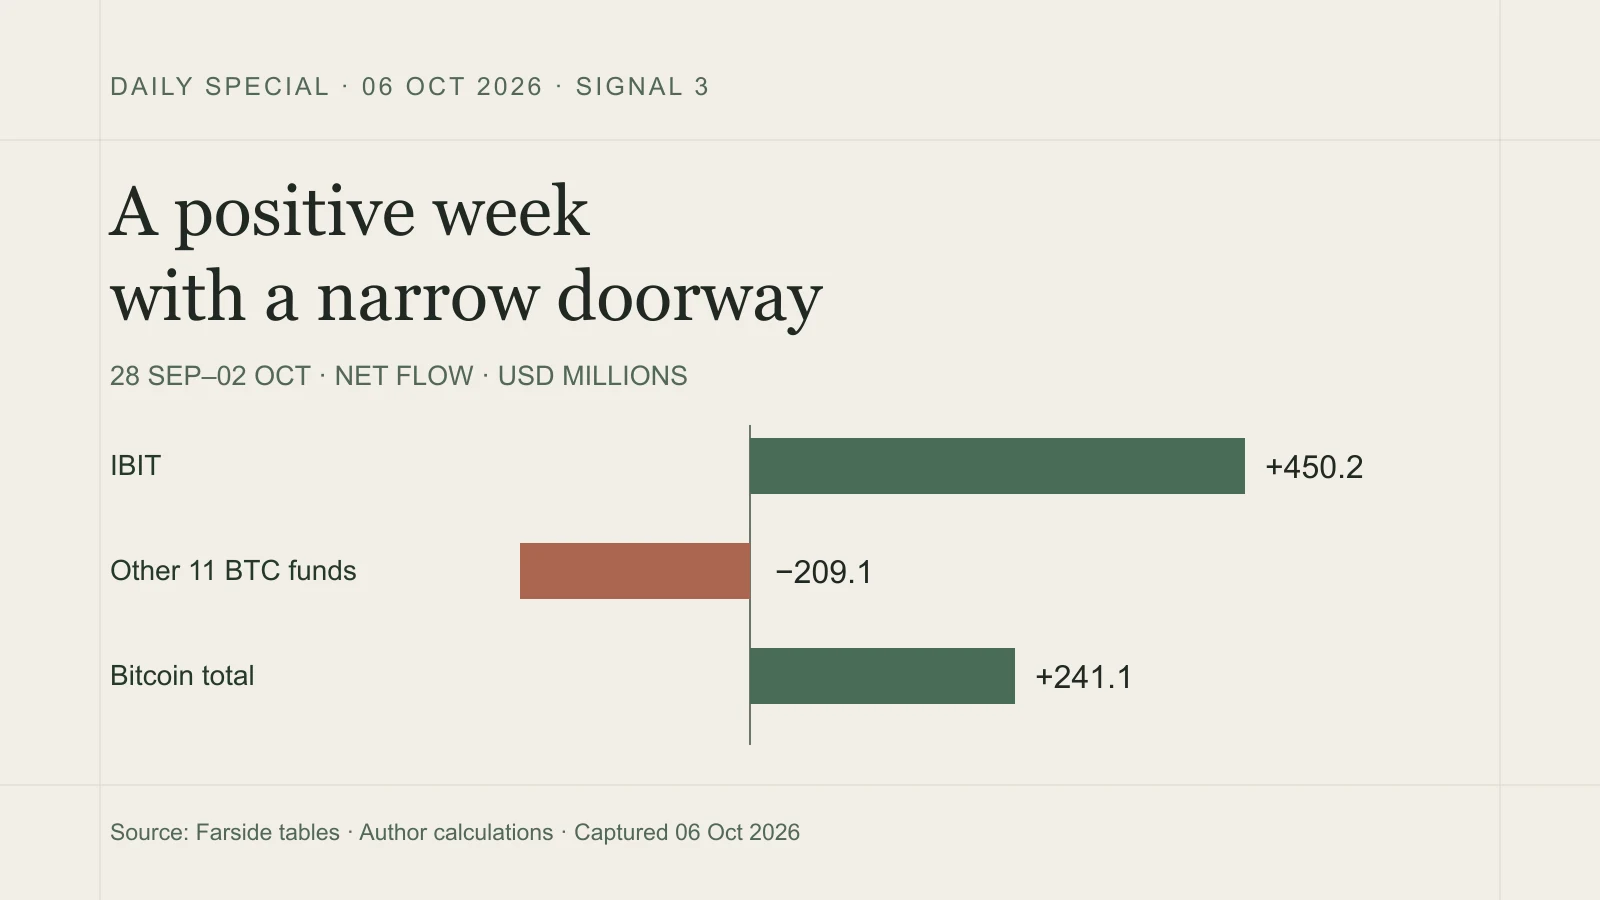
A matched five-session Bitcoin and Ether fund-flow reconciliation, fund-level breadth and a separate incomplete October 5 snapshot.
Bitcoin funds finished the week in positive territory. Remove one fund from the arithmetic, and the rest finished in the red.
That is the puzzle inside the five US trading sessions from September 28 through October 2. Adding Farside’s Bitcoin rows gives $241.1 million of net inflows. IBIT alone contributed $450.2 million. The other eleven funds together contributed −$209.1 million.
A positive total can be perfectly correct while our mental picture of a crowd rushing through the door is wrong. Here, I would start by asking how many doors were actually busy.
Put both markets on the same calendar
Ether supplies a useful comparison. Across exactly the same five sessions, Farside’s Ether table adds to −$138.1 million. All fund cells in these ten market-day rows contained numbers when reviewed on October 6, Hong Kong time. Their sums reproduced the displayed daily totals.
Amounts below are in millions of US dollars; a minus sign means net outflow.
| US session | Bitcoin | Ether |
|---|---|---|
| September 28 | +31.0 | +17.1 |
| September 29 | +66.2 | −2.8 |
| September 30 | −148.7 | −59.6 |
| October 1 | +102.7 | −55.4 |
| October 2 | +189.9 | −37.4 |
| Five sessions | +241.1 | −138.1 |
Both series were positive on Monday and negative on Wednesday. They went in opposite directions on the other three days. Calling this a week of uniformly returning crypto demand would smooth away most of what makes it interesting.
Open the total and count the funds
Four of the twelve Bitcoin funds had positive net flows for the week, five had negative flows and three showed zero. Ether had one positive fund out of eleven: TETH, at $1.7 million. Six Ether funds were negative and four showed zero. These are counts of funds, with each receiving one vote regardless of size. They do not count investors.
IBIT’s contribution exceeded the entire Bitcoin group’s net gain because other funds offset it. The subtraction is useful precisely because it is modest: 241.1 − 450.2 = −209.1. It describes the observed composition. It does not predict what the market would have done if IBIT had never existed.
Nor can we turn the difference between Bitcoin and Ether into a rotation story. The tables do not identify the same investor selling one and buying the other. Their dollar totals also lack a common asset-base denominator. We can say the reported flows diverged; we cannot rank demand intensity or expected returns from those totals alone.
Monday has not finished reporting
October 5 belongs to the next week. In the captured Bitcoin row, ten funds had numeric entries, but IBIT and BRRR still had dashes. The displayed −$159.7 million matched the available entries. Ether showed −$18.9 million, with ETHA and ETHB still absent. Bitcoin · Ether
Those subtotals are useful observations with unfinished edges. I have left the missing cells unfilled in the calculation sheet. Adding them to last week would mix a different calendar with incomplete coverage. Even the sign of Monday’s eventual result remains unsettled by this snapshot.
A narrower claim travels further
There is also a boundary around what “flow” describes. IBIT’s 2025 annual report separates secondary share trading from creation and redemption. A person buying an existing share from someone else is not, by that act alone, creating a new fund share. The report explains the machinery; it does not independently certify these October numbers.
This reconciliation uses Farside’s own published aggregation. I checked its arithmetic, not every underlying issuer report. The provider warns that its automatically updated tables may contain errors, and later corrections can change the result. No current network-activity series was collected here.
The useful conclusion is specific: the completed week showed positive Bitcoin flows concentrated in IBIT, alongside net Ether outflows. That is enough to revise an overly broad headline. It is not enough to declare a market regime or make a portfolio decision. I would rather keep the small, defensible finding than lend a very large story to one busy doorway.
Sources and calculation sheet
The three sources below were reopened on October 6, 2026. The downloadable reconciliation includes each fund’s weekly sum, the matching daily rows, the incomplete October 5 cells and the calculation method.