INVEST · Research → story
The minus sign survived the relief
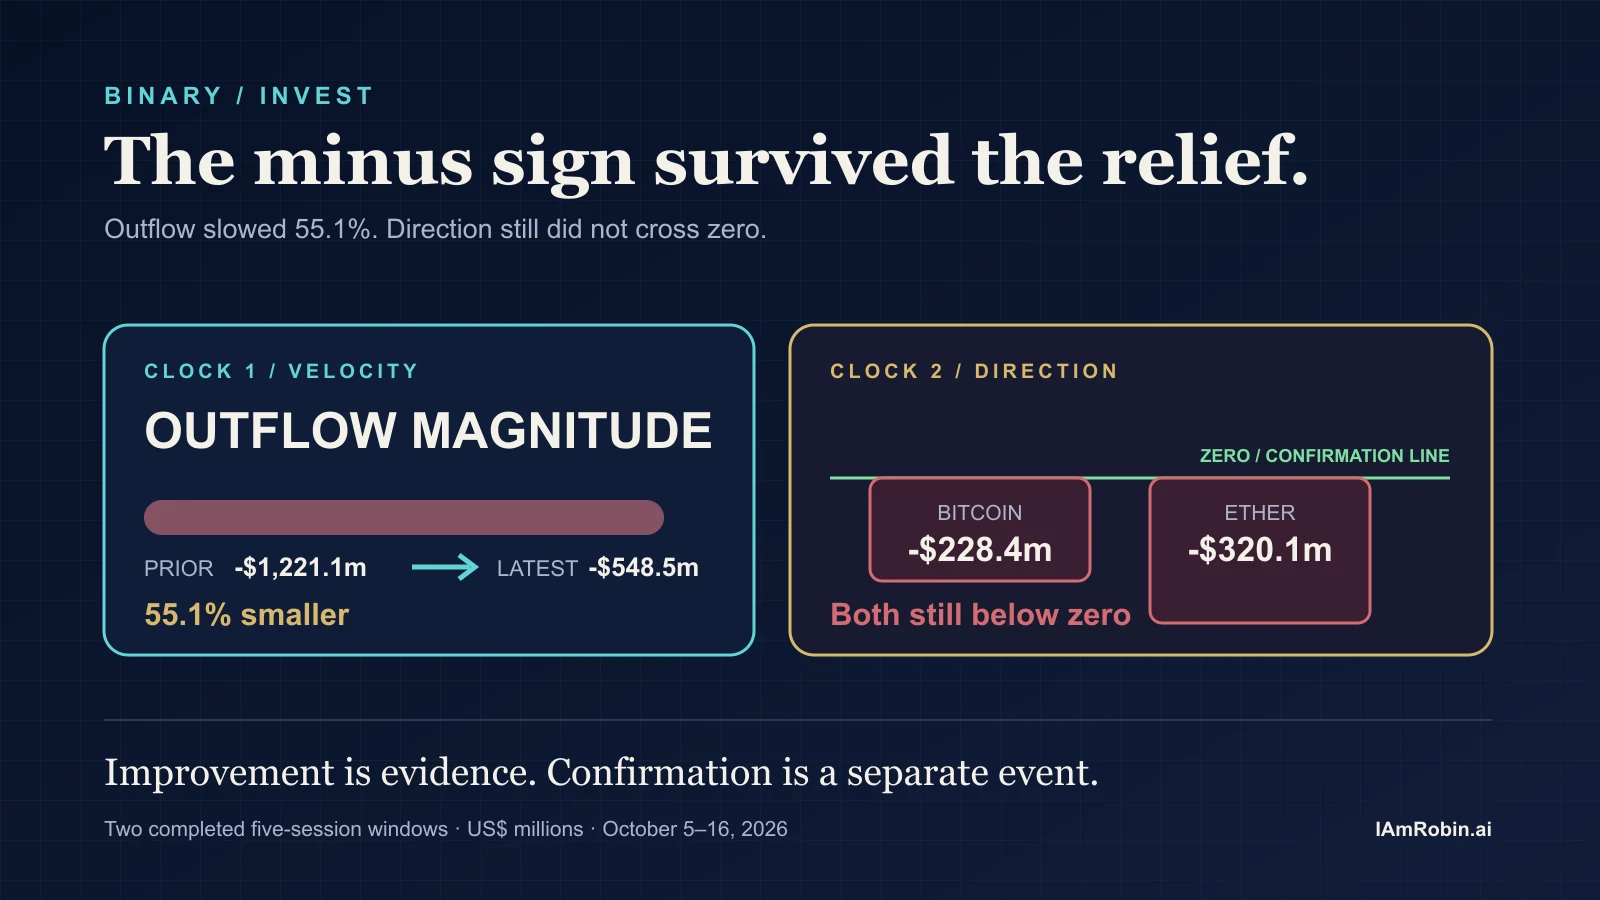
Combined outflow shrank 55.1%, yet the Bitcoin and Ether five-session totals stayed negative. Better velocity is not a change in direction.
Sometimes the most persuasive number is the one that merely got less bad.
Across two adjacent five-session windows, the combined outflow from the displayed U.S. spot-Bitcoin and spot-Ether ETPs fell from $1.2211 billion to $548.5 million. That is a 55.1% reduction in outflow magnitude. It deserves attention.
It does not deserve a new sign.
The latest Bitcoin window was still -$228.4 million. Ether was still -$320.1 million. Relief arrived. Reversal did not.
One scoreboard, two questions
A capital signal often has two clocks running at once.
The first asks about direction: is the completed-window total above or below zero?
The second asks about velocity: is the negative total expanding or shrinking?
This sample gave different answers. Velocity improved sharply. Direction stayed negative. Both statements are true, and neither cancels the other.
The trouble begins when a better second answer quietly edits the first. A shrinking outflow becomes “money is coming back.” A slowing decline becomes “the turn.” The arithmetic has not crossed the line, but the story has.
For this comparison, the line was fixed in advance: call the flow picture broader only when both Bitcoin and Ether five-session sums are positive together. The rule is not glamorous. That is useful. A dull rule is harder for one exciting day to seduce.
One green day can borrow a whole week’s narrative
October 13 was the tempting day. Bitcoin products showed $175.7 million of net inflow, while Ether products showed $24.8 million. It was the only session in the ten-day sample when both groups were positive.
Then three of the next four combined daily totals were negative.
The green day was real. So was its limited reach. It changed the path of the rolling window without carrying that window above zero.
This is a common measurement trap. A vivid observation arrives faster than the slower statistic designed to absorb noise. The observation earns the headline; the window keeps the memory.
A broad headline passed through a narrow doorway
The latest totals also looked wider than their issuer-level contribution.
For Bitcoin, IBIT and FBTC together accounted for $225.6 million of the group’s $228.4 million outflow, almost 99%. For Ether, ETHA accounted for $299.0 million of the $320.1 million total, about 93%.
That concentration does not make the totals false. It changes what they can support.
“Crypto money left” sounds like a population story. The rows show something narrower: primary-market flow estimates around a small set of listed products, with most of the latest movement concentrated in three issuer lines.
The tables do not reveal motive. They cannot tell us whether an institution changed exposure, an authorized participant adjusted inventory, or investors moved between products. Contribution is arithmetic. Intent is still missing.
The pipe is not the building
The SEC permits authorized participants to create and redeem crypto ETP shares in kind. That mechanism connects listed shares with deliveries of the underlying asset or cash through a specialized primary market.
It is one pipe, not the whole building.
Fund shares also trade between investors in the secondary market. A creation or redemption table is not a count of buyers and sellers. It does not measure network use, explain every flow, or predict the next price move.
This narrower reading is not a weakness. It is what keeps a useful measurement useful.
Put confirmation after improvement
The cleanest way to use an improving negative signal is to preserve its place in the sequence.
First, record that pressure eased. Then check whether the sign changed. Then ask whether the movement was broad or concentrated. Only after that should the measure be compared with other evidence such as price, basis, liquidity or a clearly defined network-use series.
That sequence does not produce a trade. It protects the language around a measurement.
The relief was real. So was the minus sign.
A disciplined process can hold both truths without forcing one to impersonate the other.
Sources: Farside Bitcoin ETF flows, Farside Ethereum ETF flows, and the SEC’s in-kind creation and redemption announcement. Figures cover the completed sessions in the source Special’s October 5–16 comparison. Farside says its tables update automatically and may contain errors; the issuer records were not independently rebuilt.